You’ve tried budgeting before. Maybe you downloaded an app, maybe you built a spreadsheet with color-coded categories, maybe you sat down on a Sunday night determined to finally “get your finances together.” And for a week or two, it worked. Then real life happened — a friend’s birthday dinner, a car repair, a random Tuesday where you just needed to order takeout — and the whole system fell apart. Not because you’re bad with money. Because most budgets are built to be broken.
Traditional budgeting treats every dollar as either “allowed” or “not allowed,” which sounds disciplined but actually creates the same problem as restrictive diets: the moment you go slightly over one category, the whole plan feels like it failed, so you abandon it entirely. That’s not a willpower problem. It’s a design problem.
A budget that actually lasts isn’t the one with the most detailed categories or the strictest limits — it’s the one flexible enough that a bad week doesn’t blow up the whole month. That’s what this guide walks you through: a complete system, not just a philosophy, with the exact steps, numbers, and adjustments to make it work for your actual life.
Why Most Budgets Fail Within a Few Weeks
Before building something better, it’s worth understanding exactly why the typical approach doesn’t stick — because the failure isn’t random, it’s structural.
Too many categories. Twelve line items for groceries, dining out, entertainment, subscriptions, gas, and so on sounds thorough, but it also means twelve places to feel like you’ve failed. Tracking becomes a part-time job, and most people quit the tracking before they quit the spending.
Zero flexibility built in. A rigid “$200 for dining out, no exceptions” category doesn’t account for the fact that some months genuinely need more flexibility than others — a friend’s wedding, a work trip, a rough month where cooking every night just isn’t happening.
No distinction between spending that matters and spending that doesn’t. Not all overspending is equal. Going over on rent is a real problem. Going over on coffee by $15 is not. Most budgets treat every category with the same seriousness, which makes small, harmless overages feel just as alarming as genuinely risky ones.
It’s built around restriction, not direction. A budget that only tells you what you *can’t* do gives you nothing to actually aim for. The systems that last give you a clear target to work toward, not just a list of limits to avoid breaking.
It ignores that willpower is a limited resource. Every time a budget asks you to make a fresh decision — “can I afford this specific $12 lunch out of my specific $340 dining budget” — it draws on the same mental energy you’re using everywhere else in your day. A system with fewer decision points isn’t lazier. It’s more sustainable.
The 3F Budget System: Fixed, Flexible, Future
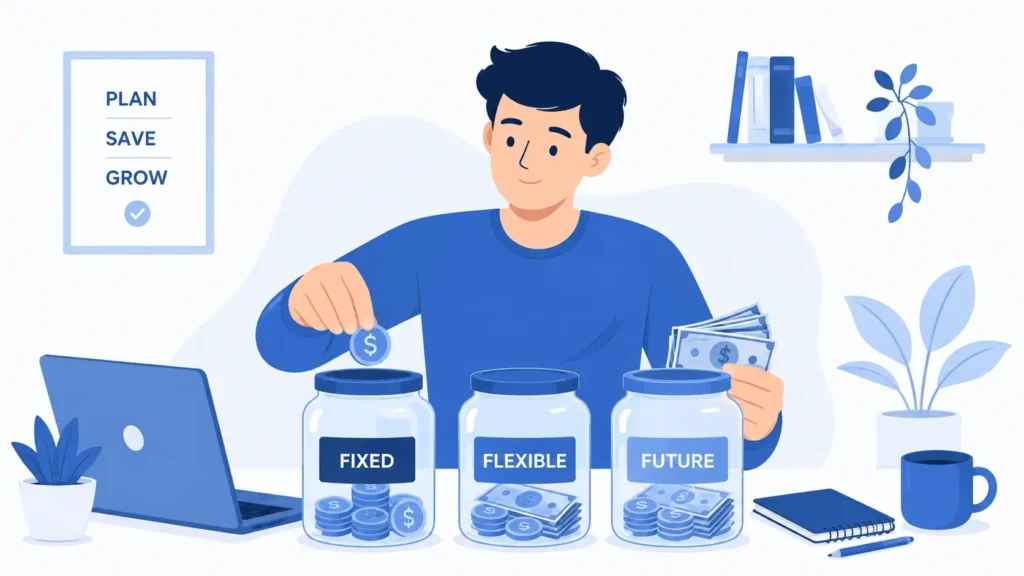
Instead of a dozen narrow categories, this approach groups every dollar into just three buckets. Fewer categories means less tracking overhead, and each bucket has a different *rule*, which is what actually makes it flexible instead of restrictive.
1. Fixed — the money that isn’t up for debate
This is everything that happens automatically every month regardless of how you’re feeling about money: rent or mortgage, utilities, insurance, minimum debt payments, subscriptions you’ve deliberately kept. The rule here is simple — these get paid first, no negotiation, no “I’ll figure it out later.” Fixed costs are the foundation everything else sits on, and treating them as non-negotiable removes an entire category of decisions from your plate.
What goes here: rent/mortgage, utilities, insurance, phone bill, minimum loan payments, any subscription you’ve consciously decided to keep.
2. Flexible — the money you actually get to enjoy, on purpose
This is where traditional budgets go wrong — they either ignore this category or micromanage it into twelve sub-categories. The 3F system treats Flexible spending as one single pool: groceries, dining out, entertainment, shopping, hobbies, all of it combined into one number you can move around freely *within* the month.
The key shift: instead of asking “did I stay under $80 on dining out this week,” you ask “am I still within my total Flexible amount for the month.” That reframing alone removes most of the guilt-driven abandonment that kills traditional budgets — spending more on a dinner out one week just means less for something else later, not a broken system.
What goes here: groceries, restaurants, entertainment, clothing, hobbies, gifts, miscellaneous purchases.
3. Future — the money working for you later
This bucket covers savings, investments, an emergency fund, and any debt payments beyond the required minimum. The critical rule that makes this bucket actually work: it gets funded first, immediately after Fixed costs, before Flexible spending happens — not whatever happens to be left over at the end of the month. Treating Future money as a bill you pay yourself, rather than a hopeful leftover, is the single biggest factor in whether savings actually accumulate.
What goes here: emergency fund contributions, retirement savings, investment contributions, extra debt payments, any specific savings goal (a trip, a down payment, a big purchase).
Worked Example: Setting Up the Numbers
Abstract percentages are easy to nod along to and hard to actually apply. Here’s a full walkthrough with real numbers, using a $4,000/month take-home income as the example — adjust proportionally to your own.
Step 1 — Total income: $4,000/month (take-home, after taxes).
Step 2 — List and total Fixed costs:
– Rent: $1,400
– Utilities: $150
– Phone: $60
– Insurance: $120
– Minimum debt payments: $200
– Fixed total: $1,930 (about 48% of income)
Step 3 — Set the Future percentage. Starting conservatively at 15%: $4,000 × 0.15 = $600/month, split however makes sense (e.g., $300 to an emergency fund until it’s fully built, then redirected to retirement or investments; $300 to retirement contributions).
Step 4 — Whatever remains is Flexible: $4,000 − $1,930 − $600 = $1,470/month for groceries, dining out, entertainment, and everything else day-to-day.
Step 5 — Convert Flexible to a weekly number for easier tracking: $1,470 ÷ 4.3 weeks ≈ $340/week. This is the number worth actually keeping in your head — not the monthly total, which is harder to feel intuitively, but “roughly $340 this week” is something you can genuinely track mentally.
How to Set Up Your Own 3F Budget
Step 1: Calculate your total monthly income. Use your actual take-home pay, not your gross salary — the number that actually lands in your account.
Step 2: Total your Fixed costs. List everything genuinely non-negotiable. Be honest here — a subscription you keep meaning to cancel but haven’t counts as Fixed until you actually cancel it, not as Flexible.
Step 3: Decide your Future percentage before anything else. A common starting point is 15-20% of income, but if that feels unrealistic right now, even 5% is a legitimate starting point — the habit of automatically funding this bucket matters more than the initial amount. Set up an automatic transfer the day your income arrives, so it happens before you have a chance to spend it.
Step 4: Whatever remains is your Flexible bucket. This is the number you’re actually free to move around within the month. No sub-categories required — though if you want a loose internal split (say, “most of this is groceries and eating out”), that’s fine as a guideline, not a hard rule.
Step 5: Convert your monthly Flexible number to a weekly figure. As shown above, this makes the number far easier to track intuitively without spreadsheets.
Step 6: Check in weekly, not daily. Daily tracking is exactly the kind of overhead that makes people quit. A five-minute weekly check — “how much of my Flexible bucket is left, and how many days remain” — is enough to course-correct without turning budgeting into a chore.
Handling Irregular Expenses (The “Fourth Bucket” Trick)
One thing that trips up even well-designed budgets: expenses that aren’t monthly but still need to be planned for — car registration, annual insurance premiums, holiday gifts, quarterly dental visits, an annual software subscription. These don’t fit neatly into Fixed (they’re not monthly) or Flexible (they’re not really discretionary).
The fix: treat irregular expenses as a sinking fund inside your Future bucket. Add up everything irregular you can predict over the next 12 months, divide by 12, and add that monthly amount to your Future contribution, held separately (a labeled sub-account or a simple tracked total works fine). When the annual insurance bill or holiday season arrives, the money is already there — it doesn’t have to come out of that month’s Flexible bucket and derail everything.
Example: $600 car registration + $400 holiday gifts + $300 annual software renewals = $1,300/year ÷ 12 = about $108/month set aside specifically for these predictable-but-irregular costs.
Paying Off Debt Within the 3F System
If you’re carrying debt beyond minimum payments, the 3F system still works — the adjustment happens inside the Future bucket rather than requiring a separate system.
For high-interest debt (credit cards, most personal loans): prioritise extra payments here within your Future allocation, even ahead of other savings goals, since the interest being avoided usually outweighs what you’d earn saving or investing that same money elsewhere.
For lower-interest debt (many student loans, some auto loans): it’s reasonable to split Future contributions between extra debt payments and building savings simultaneously, rather than delaying all saving until debt is gone — an emergency fund, even a small one, prevents new debt from being created by unexpected costs.
A simple rule of thumb: if minimum payments are already inside your Fixed bucket, any *extra* debt payment beyond the minimum is a Future bucket decision, exactly like a savings contribution — it’s just a savings contribution that happens to reduce what you owe instead of growing what you hold.
How the 3F System Compares to Other Budgeting Methods
| Method | Core Idea | Where It Struggles |
|---|---|---|
| 3F System | 3 buckets (Fixed, Flexible, Future), Future funded first | Requires trusting broad categories rather than granular tracking |
| 50/30/20 Rule | 50% needs, 30% wants, 20% savings | Similar concept, but doesn’t specify order — savings often becomes “whatever’s left,” which is the exact trap 3F avoids by funding Future immediately after Fixed |
| Zero-Based Budgeting | Every dollar assigned a specific job, income minus expenses equals zero | Highly detailed, effective for some, but the granularity itself is what causes many people to abandon it after a few weeks |
| Envelope System | Cash divided into labeled envelopes per category | Very restrictive by design, difficult to use for card-based spending, hard to adjust mid-month |
The 3F system is closest in spirit to the 50/30/20 rule, but the ordering change (Future funded immediately, not last) and the deliberate reduction to just three categories are what separate it from methods that look similar on paper but fail in the same ways traditional budgets do.
A Real Example
Priya, a graphic designer, had tried three different budgeting apps over two years and abandoned all of them within a month. Each one had the same problem: fifteen categories, strict limits on each, and a sinking feeling of failure every time she went slightly over on “entertainment” because she’d said yes to a concert with friends.
She switched to the 3F system. Her Fixed costs (rent, utilities, phone, car insurance) came to about 50% of her income. She set Future at 15%, automatically transferred the day her paycheck landed. The remaining 35% became her Flexible bucket — one number, no sub-categories.
The difference wasn’t that she suddenly spent less. It was that a bigger week (that concert, a friend’s birthday dinner) no longer felt like a system failure — it just meant a quieter week following it. Six months in, her Future bucket had grown steadily for the first time in years, not because she was more disciplined, but because the system no longer relied on willpower to survive a normal month.
Adjusting the System Over Time
A budget isn’t something you set once and never touch — but the 3F system is designed so adjustments happen on a predictable schedule, not constantly.
Monthly check-in (5-10 minutes): Did Flexible spending land roughly where expected? Did Future contributions actually go out automatically? Any irregular expenses coming up next month worth flagging?
Quarterly review (20-30 minutes): Has income changed? Has a Fixed cost crept up (a subscription price increase, a rent adjustment)? Is the Future percentage still realistic, or is it time to increase it now that the system feels stable?
Annual reset: Recalculate the irregular-expense sinking fund for the coming year, revisit whether the Future percentage should increase as income grows, and confirm Fixed costs still reflect reality rather than an outdated list.
This cadence matters because constant tinkering is itself a form of the granular-tracking trap the system is designed to avoid — check in on a schedule, not every time a purchase happens.
Common Mistakes That Undermine a Budget System
Setting Future contributions too high, too fast. An overly aggressive savings percentage that leaves almost nothing in Flexible tends to collapse within weeks, the same way an extreme diet does. Start at a percentage that’s genuinely sustainable, and increase it gradually as it becomes habit.
Treating “Fixed” as a place to hide overspending. If dining out has quietly become a “fixed” weekly habit, it belongs in Flexible, not Fixed — mislabeling spending doesn’t make it disappear, it just hides it from the part of the system designed to flex.
Abandoning the system after one bad month. A month that goes over in Flexible spending isn’t a failure signal — it’s information. Look at what happened (a one-time event, a pattern worth adjusting, a Future percentage that’s unsustainable) and adjust accordingly rather than scrapping the whole approach.
Tracking every transaction manually. This system is specifically designed to reduce tracking overhead. A single weekly check-in against your Flexible total is enough — if you’re logging every coffee individually, you’ve recreated the exact granular system this approach is meant to replace.
Forgetting irregular expenses entirely. Without the sinking-fund approach above, an annual bill can feel like an emergency every single time it arrives, even though it was entirely predictable.
How This Fits Into Your Broader Systems
A budget doesn’t exist in isolation — it works best as one piece of a larger personal system rather than a separate effort competing for your attention. If you’re also working on organizing the rest of your daily life, this pairs naturally with a [Personal Life Management System](/personal-life-management-system/), where your Future bucket contributions and weekly check-ins can become one more scheduled item in your routine rather than a standalone task you have to remember on your own.
Frequently Asked Questions
What if my income varies month to month?
Base your Fixed and Future numbers on your lowest typical month, not your best one. In stronger income months, the surplus can boost your Future bucket rather than expanding Flexible spending — this keeps the system stable even when income isn’t. Consider holding one month of Flexible spending in reserve specifically to smooth over lower-income months without disruption.
What should I do with an unexpected bonus or windfall?
A simple default: split it across the three buckets rather than treating it as pure Flexible spending. A common approach is putting the majority toward Future (debt payoff or savings), a portion toward any irregular/sinking-fund needs, and the remainder as genuine, guilt-free Flexible spending — since part of the point of a sustainable system is still enjoying money, not just saving all of it.
Do I need a specific app or tool for this?
No — the 3F system works with a basic spreadsheet, a notes app, or even a simple banking app that shows your balance. The simplicity is the point; if the tool itself becomes a chore to maintain, it works against the system rather than for it.
What if I go over my Flexible bucket one month?
Treat it as information, not failure. Look at whether it was a one-time event (a wedding, an unexpected trip) or a pattern (Flexible has been tight three months running). One-time events don’t require any system change. Recurring tightness usually means your Fixed or Future numbers need adjusting, not that you personally did something wrong.
How is this different from the 50/30/20 rule?
The 3F system is a more flexible cousin of that idea. The core difference is the *order of operations* — Future gets funded immediately after Fixed, before Flexible spending happens, rather than being whatever’s left at the end. That single ordering change is what makes savings actually accumulate instead of remaining aspirational.
Should couples or families use separate 3F budgets?
Either works, depending on how you manage finances together. Some households run one shared 3F system for joint expenses; others keep individual Flexible buckets while sharing Fixed and Future. The framework adapts either way — the three-bucket logic matters more than who’s managing which bucket.
How do I handle irregular expenses like car repairs or annual bills?
Use the sinking-fund approach described above — estimate predictable irregular costs for the year, divide by 12, and fold that amount into your Future bucket monthly. For genuinely unpredictable costs (a surprise repair), that’s exactly what an emergency fund inside Future is for.
When should I increase my Future percentage?
Once the system has run smoothly for a few months and Flexible spending consistently has room to spare, that’s a natural signal to shift a bit more toward Future at the next quarterly review — small, gradual increases are far more sustainable than a large jump that immediately strains Flexible spending.